I’m baaaaaack! I’m baaaaack in the sevens agaaiinn! (Sung to the tune of Aerosmith’s Back in the Saddle)
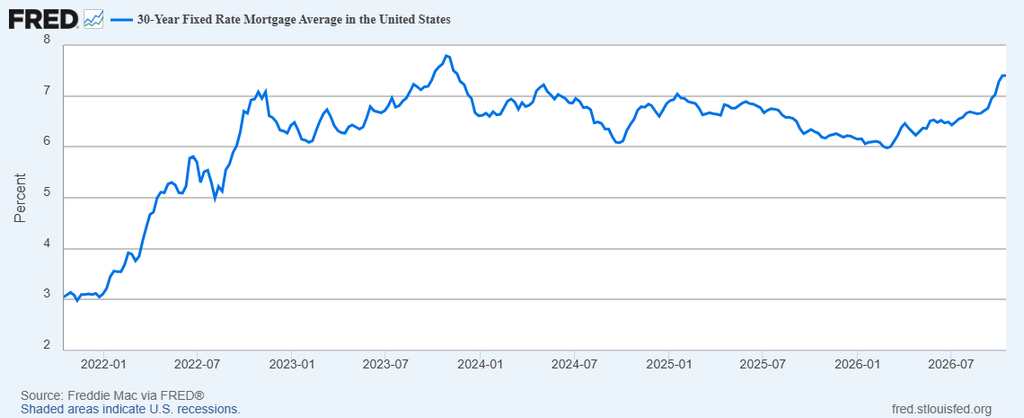
Yes, it’s true. Mortgage interest rates are back in the 7%s, for many scenarios. You can always choose to buy down to a lower rate (whether permanently or temporarily) but if you’re in the market right now, expect a rate to start with a 7%, on a primary residence, maybe high 6%s in some cases. Add roughly .5% for an investment property or second home.
Why did interest rates rise again?
Inflationary pressures remain sticky, including price pressures and uncertainty due to the ongoing war in Iran as well as between Ukraine and Russia. There’s a newly found focus on the ever-expanding US National Debt. On top of that, there’s a significant amount of corporate debt issuance to fund the AI infrastructure (data center) build-out, that buyers in the market can choose to buy vs. other debt, like Treasuries, other bonds, or Mortgage Backed Securities. Oh, and the fact that so far, at least on the surface, the US Economy continues to chug along, seemingly unperturbed by those things that are causing interest rates to rise.
Higher interest rates are generally a sign of a healthy economy and lower rates are generally a sign of a weaker economy.
Will the Federal Reserve Open Market Committee (FOMC) raise the short term Federal Funds Rate again at their meeting adjourning on Wednesday, Oct. 28 in an effort to rein in inflationary pressures? Who knows? According to CME Group’s FedWatch tool, https://www.cmegroup.com/markets/interest-rates/cme-fedwatch-tool.html the market is expecting about an 89.5% chance of their not raising rates.
I highlighted recently that the new Fed Chair, Kevin Warsh, prefers to let the market lead and the Fed to respond, rather than the other way around. So far, he seems to be getting what he wants. The market moved rates higher without the Fed needing to intervene too much, since he became Fed Chair. On top of that, it’s pretty uncommon for the FOMC to move the Federal Funds Rate, in any direction, so close to an election.
All that said, it’s important to consider that whatever the Fed does or does not do to the Federal Funds Rate, that is not a direct driver of mortgage rates. Investors buying Mortgage Backed Securities set mortgage rates based on the risk adjusted return they’re willing to accept for holding those securities.
So what happens to mortgage rates from here? There are only three possibilities:
- They stay in the same general range, bouncing somewhere between 7% and 8%, vs. between 6% and 7% as they had been.
- They take another leg higher, pressing beyond the prior high from October 2023, of 7.75% or so, perhaps creating another elevated trading range.
- They settle back down, dipping back below 7%
My base case, driven by my belief that most of the reasons we’ve seen rates rise this year are unlikely to abate in the next handful of months, is that we’re probably looking at bouncing around in the low 7%s and high 6%s through the spring and possibly into summer 2027. From there? It’s anyone’s guess.
They say history doesn’t repeat, but it does rhyme from time to time. It’s possible we’ll see a sequel to the movie we watched following the prior cycle high from Oct. 2023 through roughly September 2024.
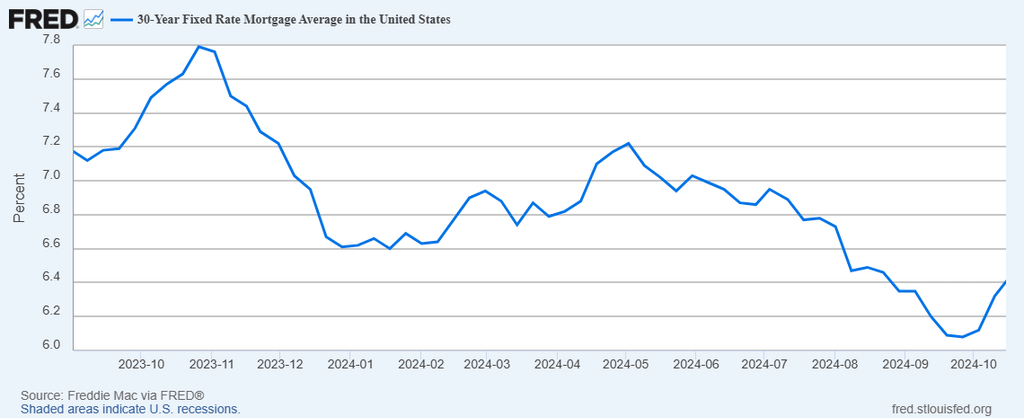
If you bought a home in the Fall of 2023 and you were paying attention to market signals, you were able to cost-effectively refinance from roughly 7.5% all the way down to roughly 6%. A similar cycle repeated again. After hitting about 7% in January 2025, mortgage rates bottomed out again close to 6% by March 2026.
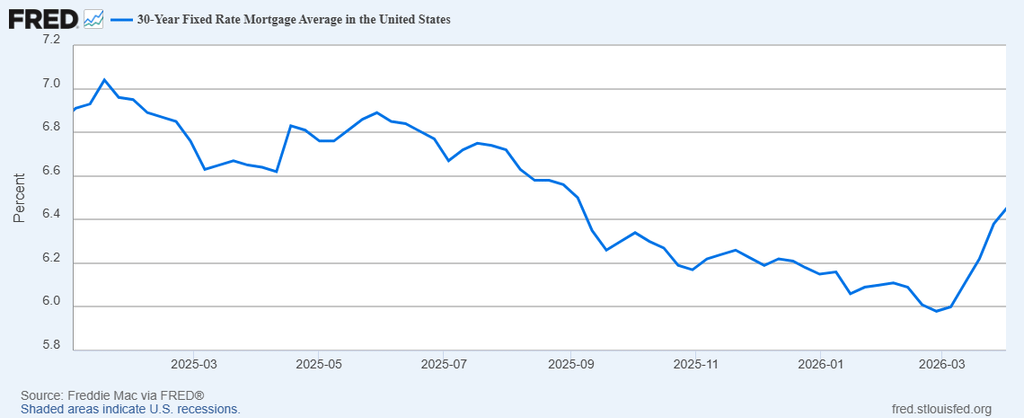
Which brings us back to where we are today:
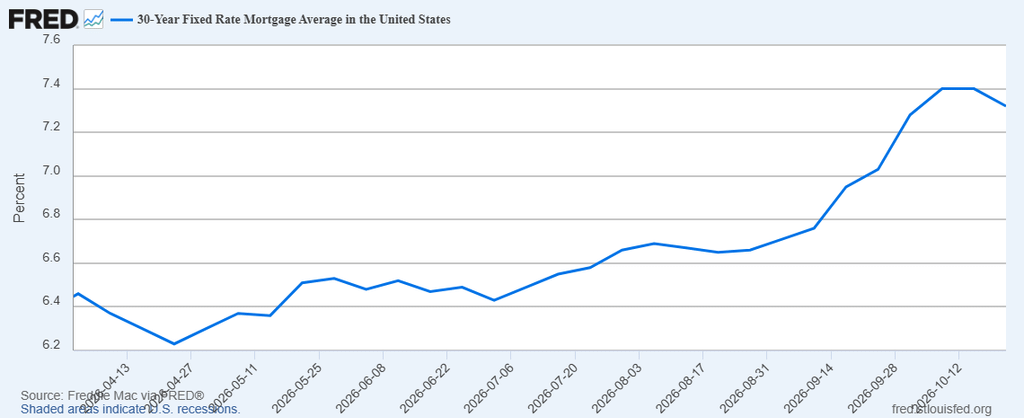
Nobody knows what the future holds and where rates will go. As I mentioned above, there are only three possibilities. Rates stay about the same. Rates increase further. Or rates drop lower again.
Given that we’ve seen two similar cycles over the last four and a half years, it’s reasonable to expect rates will dip again. When? That’s anyone’s guess.
There are also factors that could see inflationary pressures get worse, before they get better.
For prospective homebuyers, should you wait and see what interest rates do? I don’t advise that. As I always say, you buy a home for housing, or based on math if it’s an investment property. Either way, if it fits your needs and budget? Why wait? What happens if you wait and rates do take another leg higher?
Timing the market is next to impossible, and only revealed in hindsight.
There’s lots of examples, but I go back to my good friend’s Mom, who’s since passed away. She was in real estate in Santa Cruz in the late ‘70s and early ‘80s. She kept buying investment properties, including some small apartments, when interest rates were well into the double digits. People told her she was crazy. But the math worked, so she did it anyway. What happened? As rates fell from the highs of the early ‘80s, values increased, along with her cash flow as she reduced her debt service. She retired twice, by the time she was 45. When I met her in 1994, she was living in Squaw Valley, spending about 10 hours a week, managing her properties. The sad part of the story is her late in life unscrupulous attorney stole about $13million from her, as she slipped into Alzheimers, but that’s another story. Thankfully, he’s rotting in jail now.
But back to current interest rates. It’s interesting. In my 23 years as a mortgage broker, I’ve only seen two cycles with rates in the 7%s. Both were in the last four years. In the big picture, it’s tough to be in real estate right now. Affordability is hard for homebuyers. Many realtors and loan officers are leaving the business. Statistically, the average loan officer is only closing about six deals a year these days. Six deals a year! That’s crazy.
Even in what’s widely seen as a challenging real estate market, there are still roughly 350,000 existing home purchases each month in the US. That’s coupled with about 40,000 new home sales each month. Yes, that’s down from roughly 400,000/month of existing home sales during hotter markets, but that’s still a ton of volume. California alone represents about 7% of that total.
People buy homes when they need housing. At EZ Mortgages, we’re pretty fortunate. We’ve all been doing this for a long time. Heck, even a lifetime, at this point. There’s five of us, including me. We will close about 175 to 200 deals this year. About 85% of them are purchases. I’m pacing for about 30, DJ’s pacing for about 50, Nicolas might get to 100, Genelle will do 20+ it looks like, and Tony is still building his business, but he doubled last year’s volume. That’s pretty good! And we’re super thankful for you, our clients and referral partners.
We really don’t advertise. It’s all word of mouth, repeat and referral business. We’re lucky to have created a business that people appreciate. It’s a marathon, not a sprint, and we’re here for you, your family, friends and clients.
So here’s a big Thank You! We couldn’t do it without you. Literally. We hope you’ll keep those referrals coming.
With that, if you, your family, clients or friends have any questions, or would like to discuss options for buying or refinancing a home or commercial property, don’t hesitate to call me. I’m always happy to be a resource.
Here’s how rates ended this week. Have a great weekend. E
| Conforming | Rates | Points | APR | Loan Amt | Payment | ||
| 30 yr fixed mortgage | 7.000% | 0 | 7.050% | $ 400,000.00 | $ 2,661 | ||
| 15 yr fixed mortgage | 6.750% | 0 | 6.800% | $ 400,000.00 | $ 3,540 | ||
| 30 Yr fixed FHA mtg | 6.750% | 0 | 7.600% | $ 400,000.00 | $ 2,594 | ||
| 30 Yr fixed VA mtg | 6.750% | 0 | 7.180% | $ 400,000.00 | $ 2,594 | ||
| Jumbo (ask me about Super Conforming limit, per your zip code) | |||||||
| 30 yr fixed mortgage | 7.375% | 0 | 7.551% | $ 1,200,000.00 | $ 8,288 | ||
| 15 yr fixed mortgage | 7.125% | 0 | 7.373% | $ 1,200,000.00 | $ 10,870 | ||
| 7/6 ARM | 7.375% | 0 | 7.529% | $ 1,200,000.00 | $ 8,288 | ||
| 10/6 ARM | 7.375% | 0 | 7.529% | $ 1,200,000.00 | $ 8,288 | ||
| Rates subject to change without notice. | |||||||
| Please keep in mind, these rates and statistics are for informational purposes only to give you a sense of market movement and my opinion as to why. Although these rates exist today, based on certain qualifying characteristics (780+ fico, owner occupied SFR with 75% loan to value ratio or less and $200,000+ loan amount), your scenario may allow for lower or higher interest rates. Licensed by the CA Dept of Real Estate, #01760965. NMLS: 239756. Equal Opportunity Housing Lender. If you’d like to be removed from this list, please reply with REMOVE in the subject line. You can also use this link, mailto:eric@ezmortgages.us and add REMOVE to the subject line. To add someone who would appreciate this information, send me their email with SUBSCRIBE as subject. | |||||||
Broker
EZ Mortgages, Inc.
4535 Missouri Flat Rd. Ste. 2E
Placerville, CA 95667
Office: 530-303-3643
Cell: 916-223-4235
Fax: 530-237-5800
NMLS: 239756
www.ezmortgages.us